Each year, the IRS reviews contribution limits for qualified retirement plans, and for 2026, higher limits give workers more room to save. While annual increases may seem incremental, over time they can have a meaningful impact on long-term retirement readiness, especially when paired with consistent participation in an employer-sponsored plan.
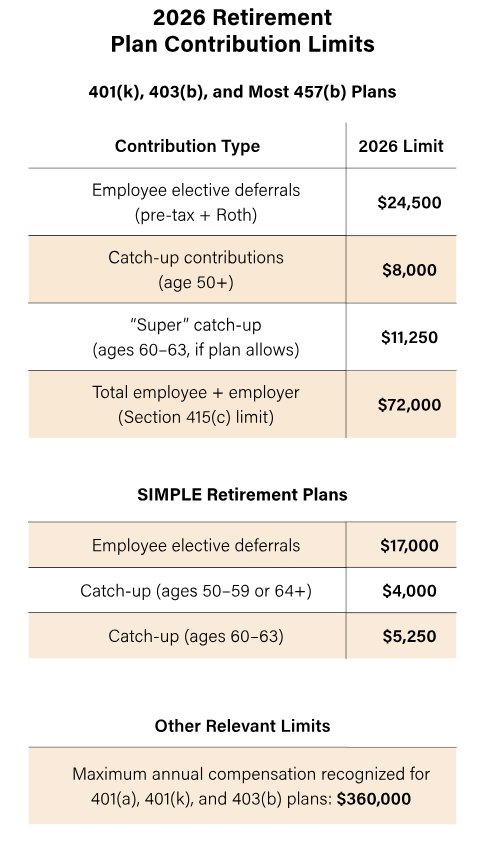
For employees under age 50, the increased limit of $24,500 means a greater flexibility to save pre-tax or Roth dollars directly from each paycheck. For those age 50 and older, the additional $8,000 catch-up contribution remains an effective way to accelerate savings as retirement approaches.
Small annual increases can make a meaningful difference over a full career.
Expanded Catch-Up Contributions for Ages 60–63
Participants ages 60 to 63 now have access to an enhanced catch-up contribution of $11,250, with 2026 marking the second year this provision is in effect. This expanded limit is designed to give workers in their peak earning years a meaningful opportunity to boost retirement savings during the critical final stretch before retirement.
Roth Catch-Up Rules for High Earners
One important reminder for 2026 is that some highly compensated employees are required to make catch-up contributions on a Roth basis. In practical terms, this means catch-up dollars are contributed after tax rather than pre-tax.
While this represents a shift change, Roth catch-up contributions can still play an important role in retirement planning by offering tax-free growth and tax-free income in retirement when used thoughtfully.
Participation Still Matters Most
Regardless of age or income level, the most important step is participation. Employer-sponsored retirement plans remain one of the most efficient and accessible ways to build long-term wealth. Even modest increases in savings, when applied consistently, can significantly improve retirement outcomes over the course of a career.
If you have questions about how the 2026 limits, enhanced catch-up contributions, or Roth catch-up rules apply to you, we’re always happy to help you understand your options and make the most of your retirement plan.